Table of Contents
A payment may look ordinary and still create a compliance risk. The value may be normal. The customer’s activity may not appear suspicious. But if the beneficiary matches a sanctions list, an intermediary institution is restricted, or information within the payment creates a potential match, the transaction may need to be reviewed before the funds move.
That is where payment screening becomes important.
Payment screening helps banks, fintechs and payment providers identify sanctions and other payment-related risks while a transaction is being processed.
In this article, we explain what payment screening is, how it works, what information is checked and how it differs from transaction monitoring.
What Is Payment Screening?
Payment screening is the process of checking information associated with a payment against sanctions, watchlists and other risk criteria before or during processing. The objective is to determine whether the payment can proceed normally or requires further review.
Depending on the payment, screening may check:
sender and beneficiary names;
banks or intermediaries involved;
countries and jurisdictions;
account information;
payment references and message fields; and
relevant sanctions or watchlist data.
Payment screening is also often referred to as transaction screening, although transaction screening can sometimes be used as a broader term. The important point is that screening generally evaluates a specific payment at a specific point in time.
For cross-border payments, FATF Recommendation 16 sets international standards around the originator and beneficiary information that should accompany payment transfers.
How Does Payment Screening Work?
An effective payment screening process can usually be broken into five steps.
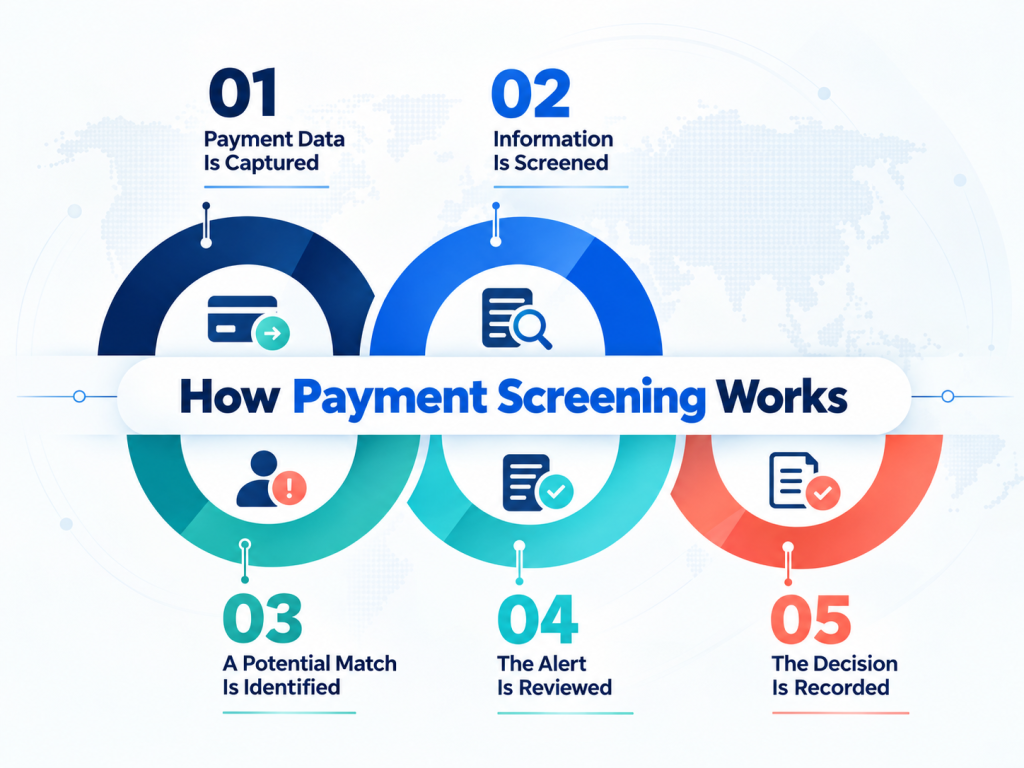
1. Payment data is captured
Relevant information is taken from the payment instruction, including the sender, beneficiary, banks involved, jurisdiction and other payment details.
2. Information is screened
he system compares relevant payment fields against sanctions lists, watchlists and other risk data, including official sources such as the UN Security Council Consolidated List where applicable. Modern screening needs to account for variations in names, spellings and aliases rather than relying only on exact matches. Relevant data is taken from the payment instruction, including transaction details used for sanctions screening against global sanctions lists and checks tied to sanctioned individuals. This captured data relates to the individual payment transaction being screened before processing continues.
3. A potential match is identified
If the system detects a possible match, an alert may be generated with a risk score. That does not necessarily mean the payment is prohibited. For example, two unrelated individuals may have similar names, which is why sanctions screening compares relevant payment fields against global sanctions data to identify sanctioned individuals before processing high risk payments and other potentially fraudulent transactions. Variations in names, spellings, and aliases can complicate matching, so multilingual sanctions screening is essential for compliance accuracy.
4. The alert is reviewed
Compliance teams can examine additional information such as geography, customer details, identifiers and payment context to determine whether the match is genuine.
If the system detects a possible match, some tools also assign a risk score to support alert prioritisation and route higher-risk cases to manual review. These alerts can reflect potentially fraudulent transactions or high risk payments, not only sanctions-name similarities, and may require further investigation to avoid missed risks. Both processes aim to prevent fraudulent transactions before funds move.
The payment may then be: Released → Held → Escalated → Rejected or Blocked
5. The decision is recorded
The institution should retain a clear record of what was screened, why an alert was generated and how the final decision was reached.
What Does Payment Screening Check?
Payment screening is not simply about checking whether the transaction amount is unusual.
The focus is often on who is involved in the payment and whether there is a reason the transaction requires intervention.
Check | Example risk |
|---|---|
Sender | Sanctions or watchlist match |
Beneficiary | Restricted individual or entity |
Intermediary bank | Sanctioned or restricted institution |
Country | Restricted or higher-risk jurisdiction |
Payment message | Potential sanctioned name or entity |
Internal list | Previously restricted counterparty |
For cross-border payments, several institutions and parties may be involved, which makes accurate payment data particularly important.
In India, regulated entities should also consider requirements under the RBI Master Direction on KYC, including obligations relating to individuals and entities designated under applicable UN sanctions regimes.
Payment Screening vs Transaction Monitoring
These controls are closely connected, but they do different jobs.
Payment Screening | Transaction Monitoring |
|---|---|
Checks an individual payment | Analyses activity over time |
Often happens before/during processing | Operates continuously or in real time |
Focuses on parties, sanctions and payment information | Focuses on behaviour and transaction patterns |
May stop or hold a payment | Usually generates an alert for investigation |
Consider two examples. A customer sends a payment to a beneficiary whose details closely resemble a sanctioned entity. Payment screening should identify that risk. Screening also applies to domestic transactions, although cross-border payments often add complexity.
Now imagine a customer makes 20 small transfers across several accounts before the money is rapidly consolidated. There may be no sanctions match at all. Instead, transaction monitoring may identify the unusual behavioural pattern by analysing transaction data, supporting risk assessment, and flagging suspicious transactions. This is why financial institutions generally need both controls.
Common Challenges in Payment Screening
False positives
A similar name does not always mean the same person. Overly broad matching can therefore generate large numbers of alerts and delay legitimate payments.
Speed
Instant and digital payments leave compliance teams very little time to identify potential risk before settlement, especially as real time payments and instant payments increase throughput and compress review windows. Overly broad matching can create large alert volumes, and false positive rates can reach 30-50% in legacy systems. Better-tuned or automated payment screening, supported by effective ways to reduce false positives in AML screening, can reduce false positive rates below 5%.
Poor payment data
Incomplete names, missing identifiers or inconsistent formatting can make accurate screening more difficult.
Changing sanctions information
Sanctions and restrictions change regularly, so screening depends heavily on up-to-date AML watchlist screening and sanctions data shaped by regulatory bodies and payment screening regulations. In practice, teams also need to stay ready for regulatory scrutiny. ACH transactions increase exposure to financial crime risks when payment data is incomplete or inconsistent.
Fragmented investigations
If payment data, customer information and alerts sit in different systems, analysts may spend more time gathering context than investigating the actual risk.
Sanctions and restrictions change regularly, and payment screening regulations evolve over time as regulators work to protect financial systems. Institutions need to track updates from relevant regulatory bodies and adapt quickly to increasing regulatory scrutiny. Centralized case management, configurable rules and regular model reviews support stronger operational efficiency without reducing control.
Best Practices for Payment Screening
Financial institutions can improve screening effectiveness by focusing on a few fundamentals and selecting strong AML watchlist providers for sanctions screening:
Use good-quality payment data: Better identifiers make potential matches easier to resolve.
Keep screening data current: Sanctions and watchlists should be updated quickly as changes occur.
Tune matching thresholds: Rules should identify meaningful matches without creating unnecessary alert volumes and support continuous fraud monitoring and prevention.
Review false positives regularly: Recurring false alerts can reveal areas where matching logic needs improvement.
Connect screening with investigations: Analysts should be able to access relevant customer and payment information from the alert, ideally within a complete AML system that unifies screening and monitoring.
Maintain an audit trail: The institution should be able to explain why a payment was released, escalated or stopped, a capability that is central when comparing top AML software vendors and their compliance solutions.
What Should Payment Screening Software Offer?
A strong AML payment screening solution should do more than compare names against a list as part of broader risk management. Useful capabilities include:
real-time screening in screening systems;
sanctions and watchlist coverage;
fuzzy or approximate name matching;
configurable thresholds;
payment-message screening for payment service providers;
alert prioritisation that supports fraud detection;
investigation workflows;
audit trails to support sanctions compliance and help ensure compliance; and
integration with transaction monitoring in payment screening systems, which also helps build customer trust and loyalty.
The real value comes when screening is connected to the wider AML workflow.
A stronger sequence looks like: Payment → Screening → Risk Decision → Monitoring → Investigation
ZIGRAM’s Transact Comply brings payment screening and transaction monitoring into a connected environment with configurable rules, risk scoring, alerts and investigation workflows.
FAQs
Is payment screening the same as transaction screening?
The terms are often used interchangeably. Payment screening specifically refers to checking information associated with a payment, while transaction screening may sometimes be used more broadly.
Is payment screening the same as transaction monitoring?
No. Payment screening typically evaluates an individual payment, while transaction monitoring identifies suspicious patterns across customer activity over time.
What is sanctions payment screening?
Sanctions payment screening checks relevant parties and payment information against applicable sanctions lists to identify potentially restricted transactions.